The Ministry of Finance of the Slovak Republic has issued new templates of the corporate income tax return (DPPO) and the personal income tax return – type B (DPFO B). They will be used when filing returns for the 2026 tax period, meaning in 2027. The template of the personal income tax return – type A from 2025 remains in force; for taxpayers with employment income, the form does not change. Several updates require background documents that are best prepared before starting to fill in the form. We bring an overview of the most important changes.
Corporate income tax return (DPPO)
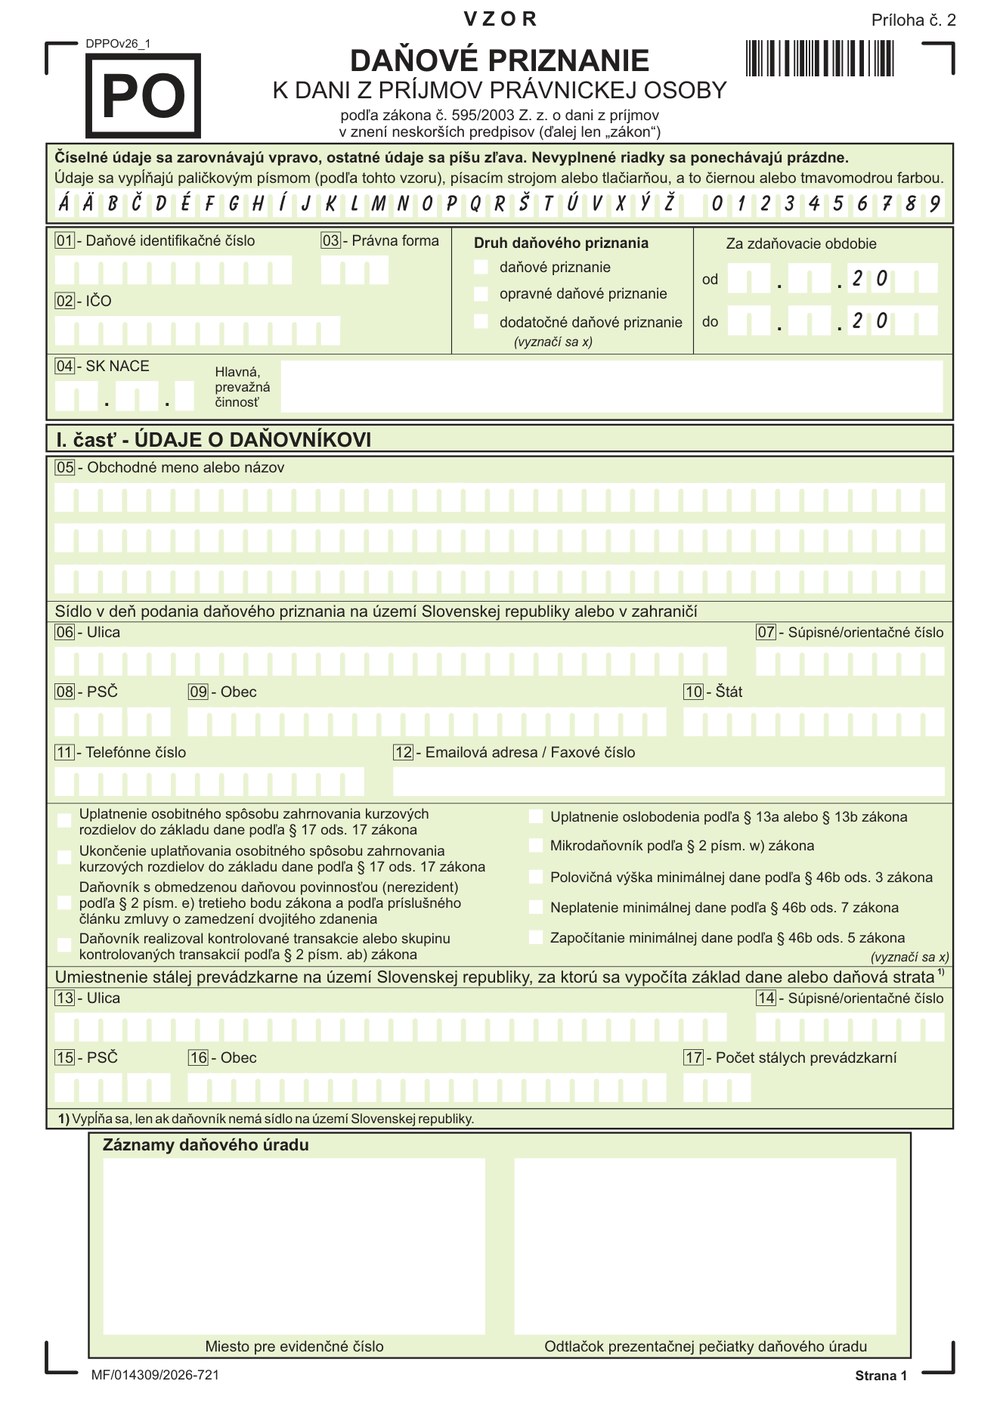
The form has 21 pages and several sections are being relocated or modified. The greatest number of adjustments concerns controlled transactions, the calculation of taxable income, and sports support.
Controlled transactions and intra-group loans
Instead of a general indication of affiliation with related parties, a company will directly declare on the first page of the tax return that it carried out controlled transactions under Section 2(ab) of Act No. 595/2003 Coll. on Income Tax. The revised Table I requires, for each transaction, its impact on the tax base, information on aggregation, and details of affiliation. If controlled transactions were carried out below the threshold under Section 17(5)(a) of the Income Tax Act, a specific checkbox under Table I is ticked. A new part is a separate overview of credits and loans with related parties, showing the highest amount during the year and the balance at the end of the year.
In practice, this means that records of intra-group transactions must be completed before starting to fill in the tax return. The impact on the tax base is stated separately for each transaction, so relying on a single aggregate figure from the header is no longer possible.
Calculation of taxable income in the tax return
The tax return is supplemented by a new Table L, in which the total taxable income is calculated step by step from booked revenues through individual adjustments to the final amount. The applied tax rate and the amount of minimum tax depend on this figure. Each adjustment will need to be specifically named and matched to the line of the return from which it originates.
Table L is therefore a bridge between the accounting result and the tax base. If a company cannot support an adjustment in its accounts, it will not be able to defend it in the tax return either.
Sports support
A separate line for expenditure on sport support has been added to the form, in which these expenses are added back to the tax base in two situations:
- Expenditure on sport support that was paid in the tax period, but the company reports a tax loss.
- Expenditure on sport support that was not paid by the end of the tax period and is therefore not a tax expense.
Anyone claiming a deduction for expenditure on sport support under Section 30ca of the Income Tax Act must also state in the annex the identification of the sports organisation (Company ID, name, registered office) and the start date of the support. It is more sensible to collect these details continuously throughout the year rather than retrospectively from accounting records.
Further changes
- a separate line for adjusting the tax base or tax loss under Section 17k of the Income Tax Act: limitation on the tax deductibility of net interest costs exceeding 3 mil. EUR to 30 % of tax EBITDA (previously part of non-deductible expenses in line 130),
- a new separate tax base under Section 51eb of the Income Tax Act for card payment fees in favour of a player's account,
- a simplified section on minimum tax,
- renumbering of lines and a shift in the numbering of individual sections.
Personal income tax return – type B (DPFO B)
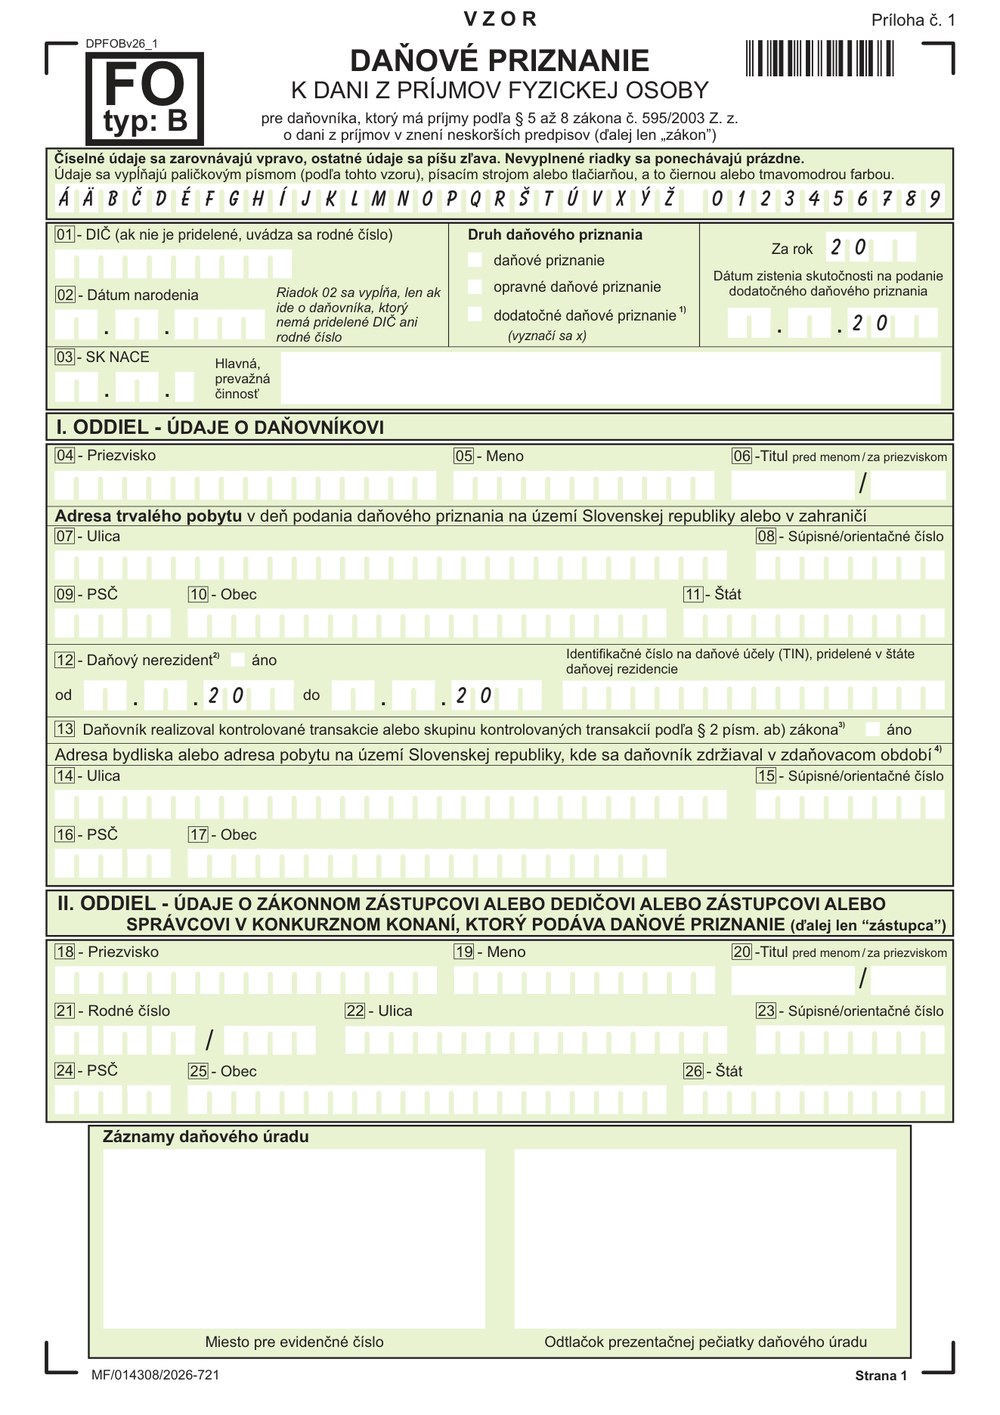
Personal income tax return – type B (DPFO B)
Template for the 2026 tax period · PDF, 20 pages
Download PDFThe form has 20 pages. The changes affect controlled transactions, taxpayers from third countries, and sports support.
Controlled transactions
Similarly, an individual will declare directly in the tax return, instead of stating affiliation, that they carried out controlled transactions under Section 2(ab) of the Income Tax Act.
Third-country nationals
Third-country nationals applying for the renewal of temporary residence will state, in a new line below Table No. 1, the amount of taxable business income under Section 6(1) of the Income Tax Act. They complete this line even if they maintain double-entry bookkeeping.
Sports support
When claiming a deduction of expenditure on sport support, Annex No. 1c newly requires the identification of the sports organisation and the start date of the support. Income from a sports sponsorship agreement in Table No. 3 for other income is now reported not only for athletes, but also for sports professionals.
Further changes
- the country of tax residence (line 145) is completed only by non-residents,
- only annexes that are actually completed are included in the number of annexes.
What to prepare before filling in the return
Both Slovak forms are completed once a year, but the background documents for them are generated throughout the entire year. If a company does not have them assembled, the completion process can stretch into several weeks. It is therefore worthwhile to review the checklist before filing:
- an overview of controlled transactions with related parties, including the impact on the tax base, aggregation, and affiliation,
- an overview of credits and loans with related parties, showing the highest amount during the year and the balance at the end of the year,
- calculation of net interest costs if they exceed 3 mil. EUR,
- identification of sports organisations that the company supported (Company ID, name, registered office) and the start date of the support,
- documents relating to card payment fees in favour of a player's account,
- for third-country taxpayers, the amount of taxable business income under Section 6(1) of the Income Tax Act.
Both forms can be downloaded in their original PDF directly in this article. When filling in the form, check that you are using the 2026 tax period version and not an older one. If you are unsure which change applies to your specific situation, we will go through it with you before filing the tax return.
The content of this article is for informational purposes only and in no way replaces professional legal, tax, or accounting advice. The company Dravecký & Partner bears no responsibility for any decisions made based on the information provided herein, nor for any potential damage that might arise from such actions. Before applying any information to your specific situation, we strongly recommend consulting with a qualified expert.
Be the first to know about the latest information from the world of taxation, accounting and auditing.